Investor overview · NYSE American: GRO · B3: GROP31

Potash for the world's largest importer.

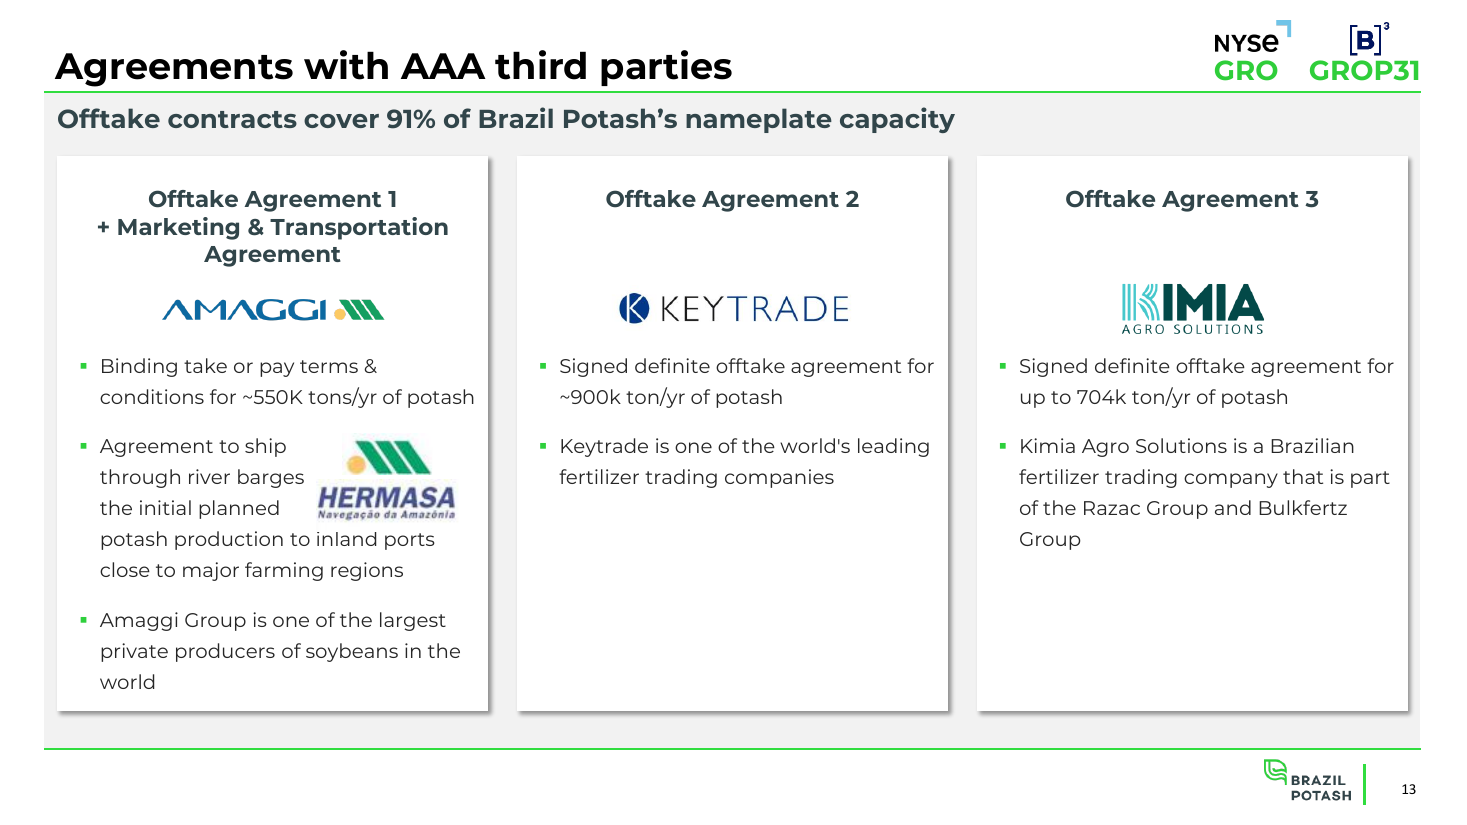
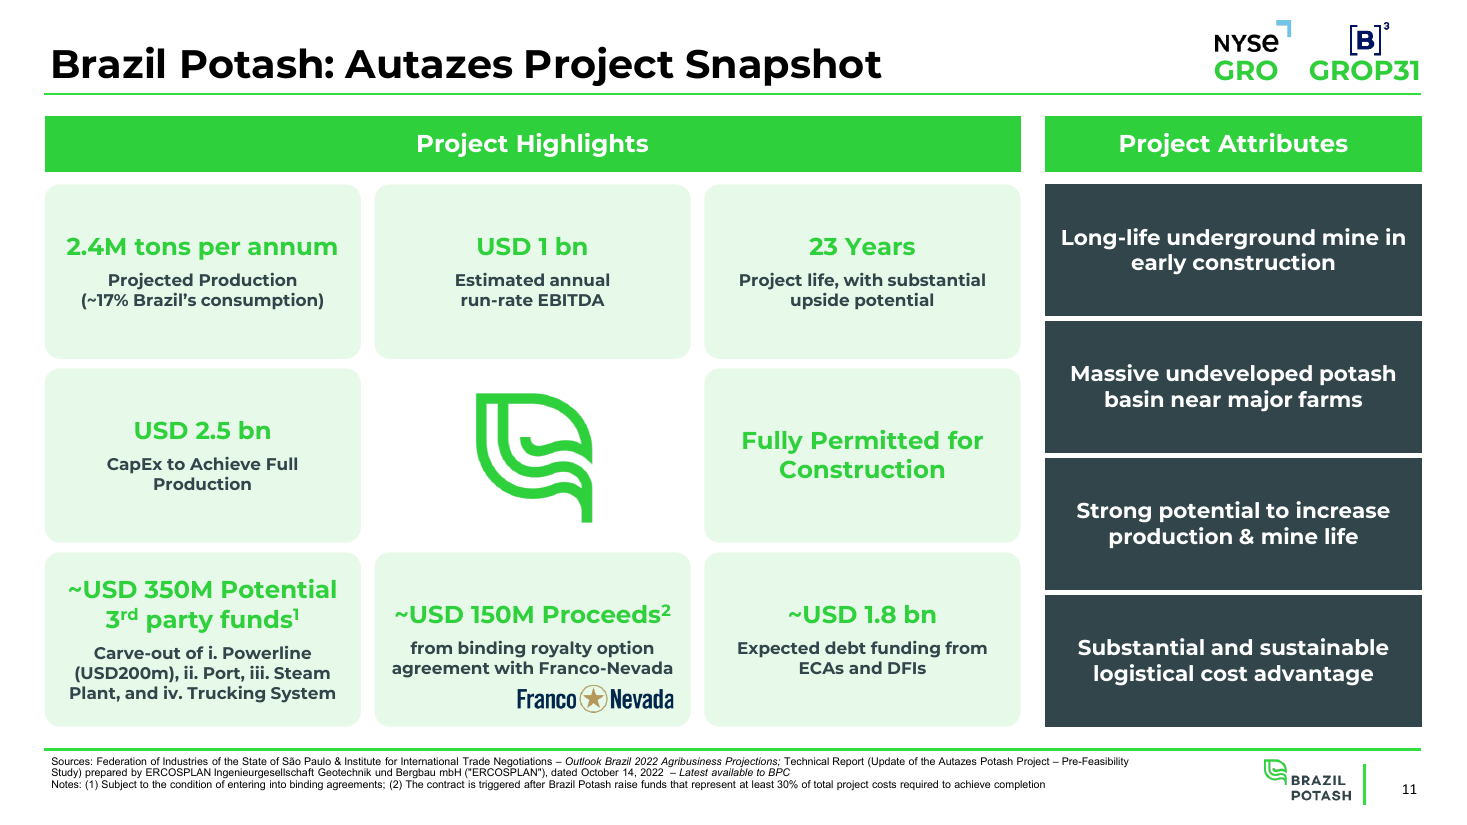
Brazil Potash is developing the fully permitted Autazes Project in Amazonas, Brazil, a 2.4 million ton per year underground potash mine with a 23-year initial life. Brazil imports about 98% of its potash; Autazes would supply roughly 17% of national demand from inside the country, with 91% of capacity already contracted to Amaggi, Keytrade and Kimia Agro Solutions.

2.4 Mtpa
Projected potash production (~17% of Brazil's demand)
US$1bn
Estimated annual run-rate EBITDA
91%
Of nameplate capacity under binding offtake
23 yrs
Initial mine life from <10% of the basin drilled
$75.7M
Cash at June 30, 2026, no debt
The opportunity

Why Autazes, why now.

Three things the Q3 2026 investor presentation makes clear.

Brazil needs its own potash

Brazil is the largest net exporter of agricultural products and takes 22% of global potash demand, yet produces under 1% of supply. About 52% of world supply sits in Russia, Belarus, Israel and Jordan. The federal government has declared potash a strategic mineral.

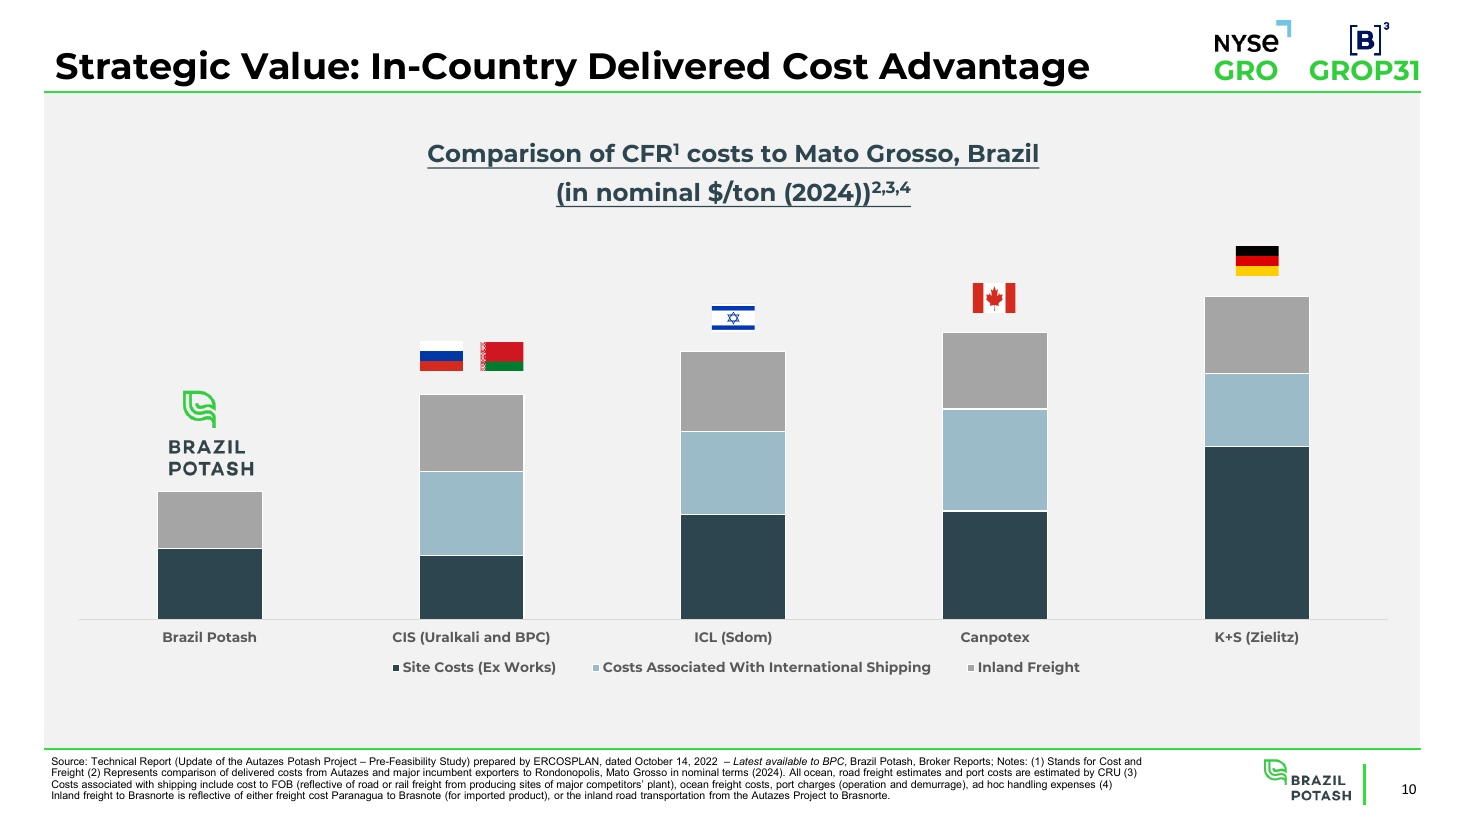
The lowest delivered cost into Mato Grosso

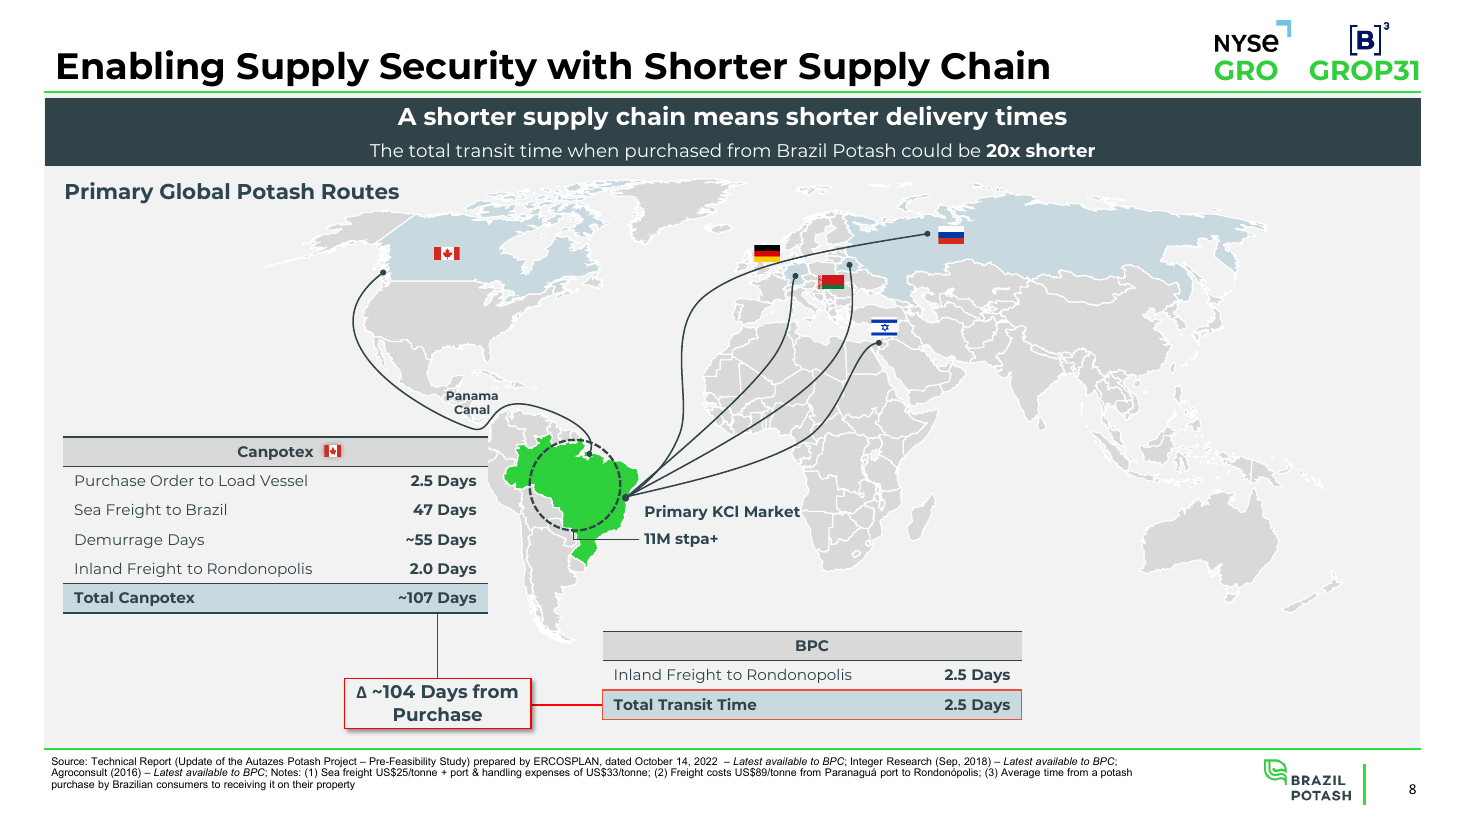
Autazes sits beside the Amazon river system, 2.5 days from the farm belt that consumes 46% of Brazil's fertilizer. Imports from Canada take about 107 days. The 2022 ERCOSPLAN pre-feasibility study puts Brazil Potash's delivered cost below every incumbent exporter.

Permitted, contracted and in early works

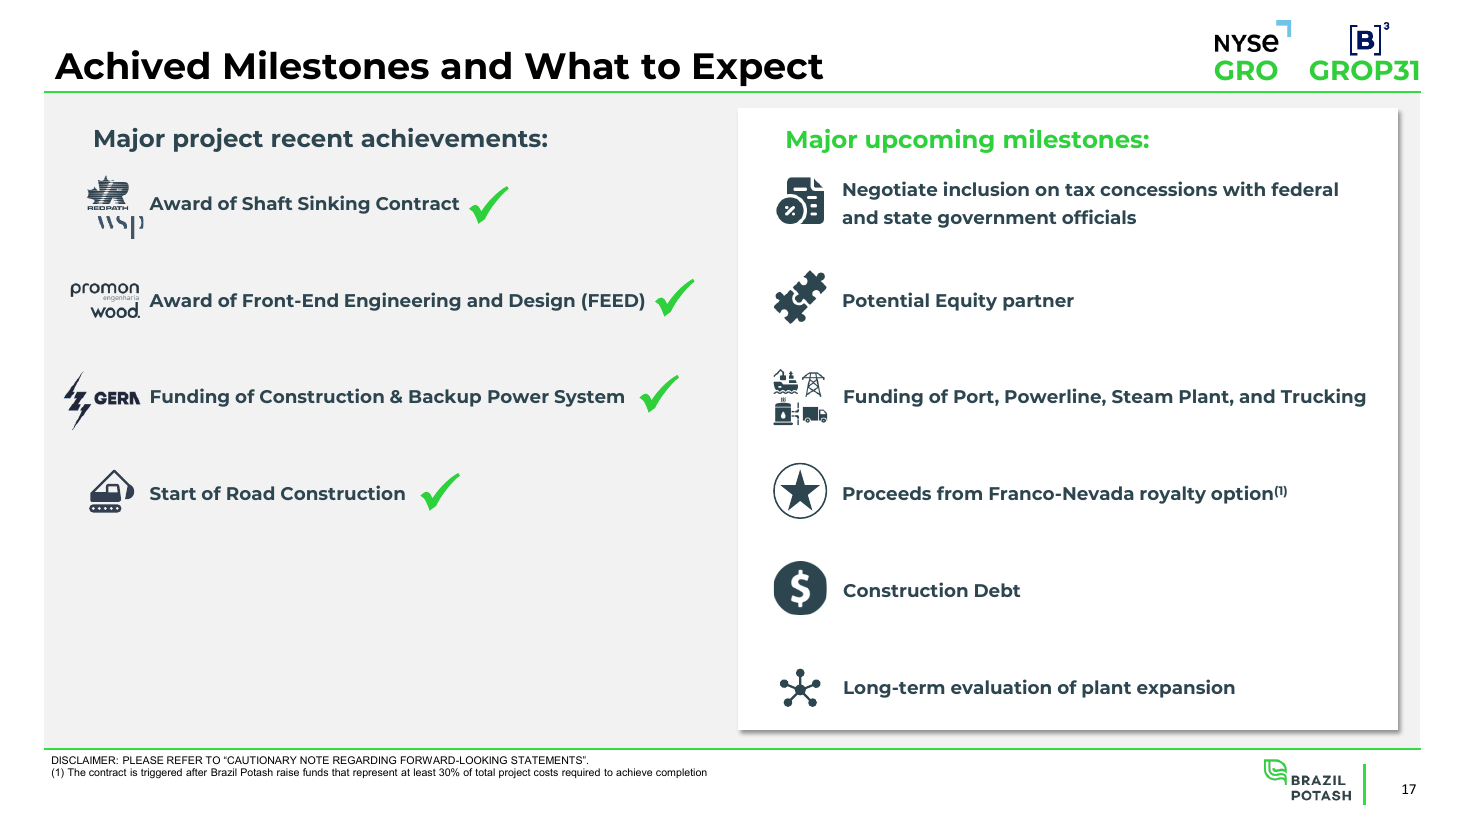
Mine and plant installation licences were granted in 2024 and water permits converted to operational permits in October 2026. FEED is awarded to Wood/Promon and WSP/Redpath Deilmann, road construction has started, and a 28-year power contract removed about US$33M of upfront capital.

From the deck

The key slides, with the takeaway.

A few pages from the corporate presentation that carry the story. Download the full deck →
The deal

A US$2.5bn build, funded in pieces.

There is no live equity offering on this page. The company closed a US$63.3M public offering of common shares and pre-funded warrants on May 4, 2026. The remaining construction capital is planned from the sources below, as laid out in the Q3 2026 presentation.

Capex to full production
US$2.5bn
Construction debt
~US$1.8bn targeted from export credit agencies and DFIs
Third-party carve-outs
~US$350M: powerline (US$200M), port, steam plant, trucking
Franco-Nevada royalty option
~US$150M, triggered once 30% of project cost is raised
Equity partner
Under discussion
Last equity raise
US$63.3M public offering, closed May 4, 2026
Paid-in capital to date
Over US$295M
Government support
Federal backing for construction financing (Sep 2026); up to ~US$94M SUFRAMA tax savings
Use of proceeds
  • Mine shafts and underground development (WSP / Redpath Deilmann FEED)Core capex
  • Process plant and surface facilities (Wood / Promon FEED)Core capex
  • Powerline, port, steam plant and trucking~US$350M, third-party
  • Construction and backup power28-year BOOT contract, no upfront capital
Brazil Potash is listed on NYSE American (GRO) and B3 (GROP31). Nothing on this page is an offer of securities. The financing sources above are plans and non-binding arrangements described by the company; the Franco-Nevada and third-party funding are subject to conditions and definitive agreements, and there is no assurance they will close on the terms described, or at all.
Who's running it

The team and their track record.

MS
Mayo Schmidt
Executive Chairman

Former chairman and interim CEO of Nutrien, the world's largest fertilizer company; former CEO of Viterra (sold to Glencore in 2012) and Hydro One.

MS
Matt Simpson
CEO & Director

CEO since 2014; former Mine General Manager at Rio Tinto's Iron Ore Company of Canada, running a US$300M a year operation; also CEO of Black Iron since 2010.

SL
Sergio Leite
President, Potássio do Brasil

40 years in large industrial, mining and infrastructure projects at Vale, CSP and Bahia Ferrovias; as CEO of Companhia Siderúrgica do Pecém raised US$2.9bn from a bank syndicate including BNDES.

RP
Ryan Ptolemy
CFO

CFO since 2011; also CFO of several TSX and Cboe Canada listed companies in mining, investment and fintech.

RB
Raphael Bloise
Project Director

50 years of construction in mining and infrastructure including Carajás, Salobo, Sossego, Albrás, Alunorte and Belo Monte.

DB
Deborah Battiston
Director

CPA; former CFO of Allana Potash (2007 to 2017) and other mineral companies.

PT
Peter Tagliamonte
Director

CEO and President of Belo Sun Mining from 2010 to 2024; former COO of Desert Sun Mining.

CJ
Christian Joerg
Director

CEO of VA Intertrading; senior roles at SALIC, MAG Commodities, Viterra, UBS and SGS.

BL
Brett Lynch
Director

Executive Chairman of Ionic Rare Earths; CEO of Sayona Mining from 2019 to 2023.

HP
Hon. Pierre Pettigrew
Director

Former Canadian Minister of Foreign Affairs and International Trade; Executive Advisor at Deloitte; director since 2010.

Partners & backers
Amaggi (offtake)Keytrade (offtake)Kimia Agro Solutions (offtake)Franco-Nevada (royalty option)Wood / Promon (FEED)WSP / Redpath Deilmann (shafts)ERCOSPLAN (PFS)
Catalysts

What happens next.

  • Aug 2024
    Fully permitted for construction
    Mine and processing plant installation licences from Amazonas state
  • Dec 2024
    NYSE American listing
    IPO; company rang the opening bell
  • May 4, 2026
    US$63.3M public offering closed
    Common shares and pre-funded warrants, underwriters' option fully exercised
  • May–Jun 2026
    FEED contracts awarded
    Surface facilities to Wood and Promon; shafts and underground to WSP with Redpath Deilmann
  • Aug 21, 2026
    Supreme Federal Court decision in the company's favour
    Follows the Court of Appeal preserving rulings favourable to the project
  • Sep 2026
    Federal support for construction financing; 28-year power contract
    Power deal removes ~US$33M of upfront capex and saves ~US$10M
  • Oct 2026
    XRT ore-sorting results; water permits made operational
    Sorting screened out ~20% of lower-grade material in initial tests
  • Next
    Tax concessions with federal and state governments
    Up to ~US$94M of SUFRAMA savings estimated
  • Next
    Equity partner and third-party infrastructure funding
    ~US$350M for powerline, port, steam plant and trucking
  • After 30% raised
    Franco-Nevada royalty option proceeds
    ~US$150M once 30% of project cost is funded
  • Next
    Construction debt
    ~US$1.8bn targeted from ECAs and DFIs
  • Longer term
    Plant expansion evaluation
    23-year reserve from under 10% of the basin drilled
Capital snapshot

Where the cap table stands.

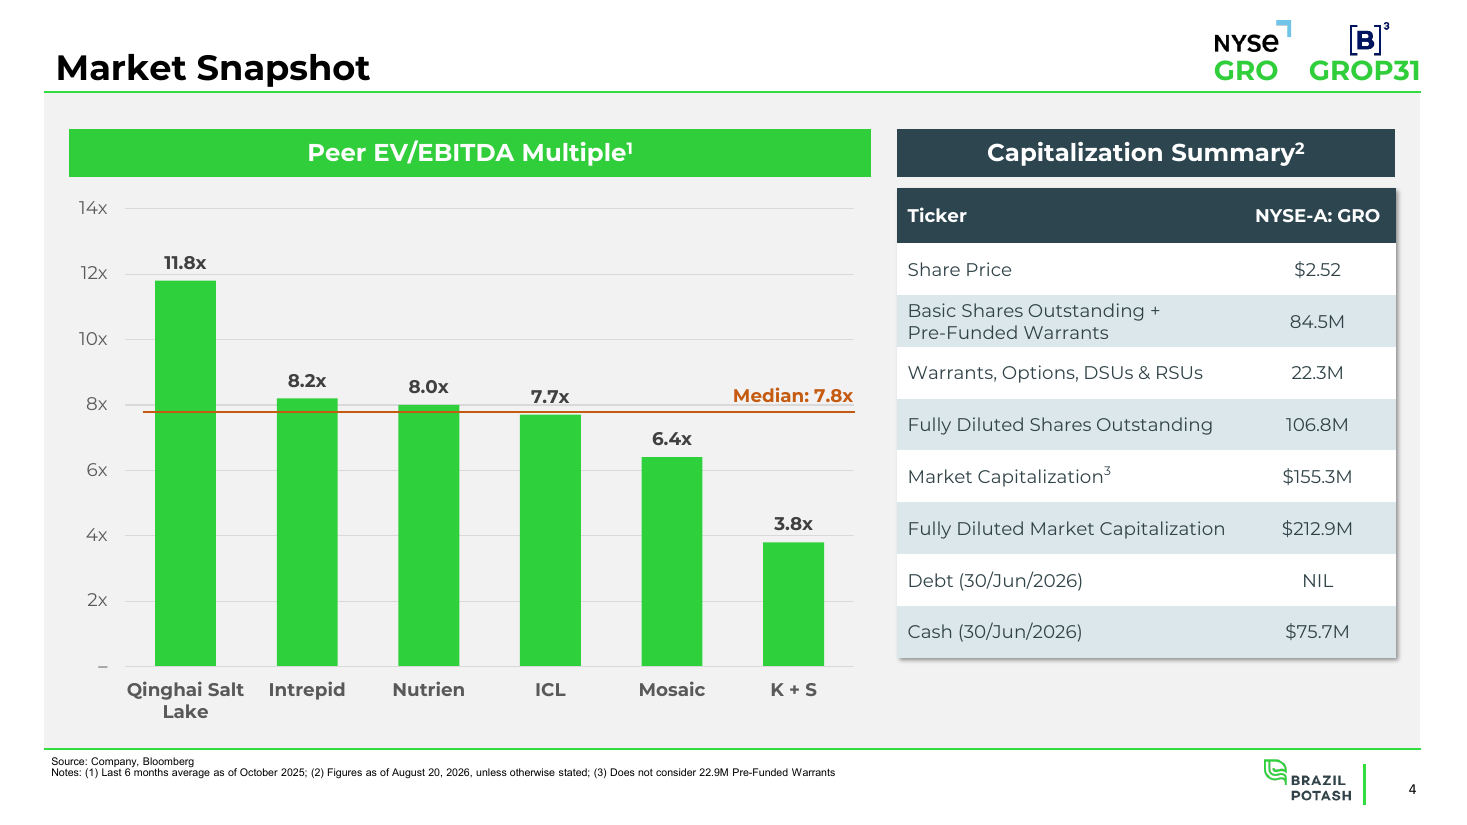
84.5M
Basic shares plus pre-funded warrants
106.8M
Fully diluted (22.3M warrants, options, DSUs, RSUs)
$155.3M
Market cap at $2.52 (Aug 20, 2026)
$75.7M
Cash at Jun 30, 2026; debt nil
$212.9M
Fully diluted market cap
$295M+
Paid-in capital to date

Per the Q3 2026 investor presentation: share data as of August 20, 2026; cash and debt as of June 30, 2026. Market cap excludes 22.9M pre-funded warrants. Share price will have moved since.

Documents

Do your diligence.

Key considerations

The questions investors ask, and where each stands.

  • Construction capital — US$2.5bn of capex against US$75.7M of cash at June 30, 2026. Further equity would dilute holders.Where it stands~US$1.8bn targeted from export credit agencies and DFIs, ~US$350M third-party funding for powerline, port, steam plant and trucking, a US$150M Franco-Nevada royalty option once 30% of the project is funded, an equity partner in discussion, and federal support for construction financing announced September 2026.
  • Permits and litigation — Licences have been challenged in Brazilian courts and can be suspended or not renewed.Where it standsMine, plant and water permits are in hand; water permits became operational in October 2026. The Supreme Federal Court (Aug 21, 2026) and the Court of Appeal (Aug 11, 2026) ruled in the project's favour.
  • Community — The project neighbours Mura indigenous lands and depends on continued local support.Where it standsFree, prior and informed consultation completed under ILO 169; a cooperation agreement with the Mura Indigenous Council was signed in March 2026, and over 90% of consultation participants voted in support.
  • Execution — This is the company's first mine, and the economics rest on a 2022 pre-feasibility study by ERCOSPLAN.Where it standsFEED awarded to Wood/Promon (surface) and WSP/Redpath Deilmann (shafts); road construction started; a 28-year BOOT power contract removed ~US$33M of upfront capital; management includes former Nutrien, Rio Tinto IOC and CSP executives.
  • Market and counterparties — Costs are in Brazilian reais while revenue follows US-dollar potash prices, and three offtakers hold 91% of capacity.Where it standsOfftake is binding with Amaggi (~550 kt/yr take-or-pay), Keytrade (~900 kt/yr) and Kimia (up to 704 kt/yr); Brazil imports ~98% of its potash, and the federal government has declared it a strategic mineral.
In the news

Latest on Brazil Potash

Headlines for Brazil Potash, Autazes potash project, pulled automatically from Google News.

Loading feed…

Loading the latest coverage…

Updates automatically. Headlines link to the original publisher. View the full news feed →
Next step

Want the full picture?

Request more information, or book a call to walk through the Autazes construction financing plan, the offtake agreements and the permitting position with the Brazil Potash team.

Request a call

Investor contact
Investor Relations
Brazil Potash Corp. · 198 Davenport Road, Toronto, ON M5R 1J2 · +1 416-861-2267
Request more information